Anthropic
ANT · NASDAQTechnologyIPO · Not trading yetThe maker of Claude has filed to list on Nasdaq as ANT. Revenue reached $17.0 billion in the September quarter and the business now brings in cash, but the founders and a trust keep control, and the price range is not set yet.
Built from the company's S-1/A filed Nov 02, 2026.
Our 0 to 100 rating, built from the filing
Unlock with IPO ProHypothetical share price
Illustration only. Dots are real funding-round prices from the ANT filing, in today's shares. In between, the line moves with 30 listed AI stocks. From Series H in June 2026 the line rises to $75 by 1 October, then follows the AI basket's October sell-off. After listing is simulated.
Deal details
- Exchange and ticker
- NASDAQ · ANT
- Price range
- Not set yet
- Our price estimate
- About $85 to $120 a share
- Shares we expect to be sold
- About 0.85 to 1.2 billion
- Company value in media reports
- $1.5 to $2 trillion
- New shares from the company
- Not set yet
- Shares sold by existing owners
- Not set yet
- Expected date
- Not set yet
- Banks running it
- 22 banks, led by Goldman Sachs and Morgan Stanley
The company sells new shares and the co-founders and other existing owners sell some of theirs. The filing leaves the price range, the number of shares and the date blank.
Our estimate, not the company's. Media reports put the IPO at $1.5 to $2 trillion and the raise at up to about $100 billion. The filing implies about 16.9 billion shares in total (846.8 million shares were 5% of all shares). $1.5 trillion to $2 trillion across about 16.9 billion shares gives roughly $85 to $120 a share, and $100 billion at those prices is roughly 0.85 to 1.2 billion shares. The last private round paid $58.90 a share in mid-2026. The real range comes in the next filing.
The IPO timeline
- First filing (S-1)Oct 26, 2026
- Amended filing (S-1/A) with September-quarter resultsNov 02, 2026
- Price range setNot yet
- PricedNot yet
- First day of tradingNot yet
Pillar breakdown
Financial strength: profits, cash flow and financial health.
How fast sales and profits grow, and how steady that is.
Moat, brand and what makes it different.
Risk: debt, cash runway, dilution and the fine print.
What protects it
- Brand. Claude is one of the best-known AI brands, with more than 11,900 customers paying $100,000 a year or more (S-1/A).
- What makes it different. Built for businesses, with coding and work agents (Claude Code, Claude Cowork) that customers keep expanding, but OpenAI and Google sell similar models.
- Market position. One of a few companies at the frontier of AI; the filing names OpenAI and Google as direct rivals and gives no market share.
What the price assumes
Worked out once the price range is filed.
What the company does
Anthropic builds Claude, a family of AI models sold to businesses through its own platform and apps, such as Claude Code and Claude Cowork, and through Amazon Web Services, Google Cloud and Microsoft Azure. The filing calls the company first and foremost a research lab, with a mission of the responsible development and maintenance of advanced AI for the long-term benefit of humanity. Most revenue is pay-as-you-go: customers pay for how much they use, priced by the model they pick. Revenue went from nothing at commercial launch in early 2023 to $17.0 billion in the three months to 30 September 2026. No single customer was more than 10% of revenue in the nine months to September 2026. It is a Delaware public benefit corporation, so the board must weigh shareholders' money interests against its stated public purpose.
Where the money comes from
Share of revenue, nine months to 30 Sep 2026 (S-1/A).
Quick facts
- Founded
- January 2021, San Francisco
- Chief executive
- Dario Amodei (co-founder)
- Employees
- About 5,300 (30 Sep 2026)
- Big customers
- 11,900+ paying $100,000 a year or more
- Net revenue retention
- About 900% (30 Sep 2026)
- Money raised before the IPO
- $141.1 billion
- Company type
- Public benefit corporation
- Website
- anthropic.com
Main competitors
The decision makers
Was vice president of research at OpenAI from 2016 to 2020 and a senior research scientist at Google Brain before that. Holds a PhD in biophysics from Princeton.
Held roles at OpenAI including vice president of safety and policy from 2018 to 2020, and was a risk manager at Stripe from 2013 to 2018.
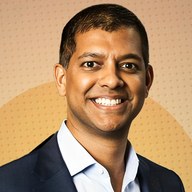
Was finance chief at Fanatics Commerce and at Cedar, and spent six years at Airbnb in corporate development and financial planning. Earlier at Blackstone and Bain.
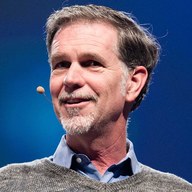
Co-founded Netflix and was its chief executive from 1999 to 2023, then executive chairman and chairman until June 2026.
What insiders paid
- Staff hold options on 1.77 billion shares, at an average exercise price of $2.91.
- In April 2026 investors bought $4.7 billion of shares from existing holders at $25.91 each. Dario Amodei, Daniela Amodei and finance chief Krishna Rao were among the sellers.
- At the Series H price, the whole company was worth about $1.0 trillion (our sum: about 16.9 billion shares on a fully diluted basis at $58.90).
Price per share of today's stock, after the 10-for-1 split of September 2026 (each preferred share converts into 10 shares). The IPO price is not set yet, so we can't compare it yet.
Who controls it
- The seven co-founders hold one special Class F share through a company they own. It carries 50.1% of the votes on ordinary shareholder matters, however many shares are sold.
- A trust of five people with no money stake, the Long-Term Benefit Trust, picks and can remove a majority of the board through its one Class T share.
- IPO buyers get Class A shares with one vote each, but all Class A shares together are capped at 49.9% of the votes.
- Many big investors hold Class N shares, which have no vote.
- Because the trust controls the board, Anthropic counts as a 'controlled company' under Nasdaq rules and can skip some of them. It says it will only do so for its nominating committee.
- As a public benefit corporation, the board must balance shareholders' money interests with the public benefit purpose.
- Anthropic gave 5% of its fully diluted shares to its own public benefit fund. The board may give it up to another 2% each time the share price rises 50% from the last milestone, starting at the IPO price.
- Each co-founder holds about 240 million Class A shares and has pledged to give 80% of their personal stake to charity. The pledge is voluntary and does not reduce their voting control.
Lock-ups
- Co-founders and holders of more than 0.5% of the shares can't sell until the second trading day after the September 2027 quarter results, or 365 days after the IPO if that comes first.
- Everyone else is locked up until the second trading day after the March 2027 quarter results, or 180 days if that comes first.
- Some shares unlock early in steps: some from the first trading day for non-founder staff and directors, then at days 27, 48, 62 and 76, then after the 2026 full-year results. The share counts are blank in the filing.
- Goldman Sachs and Morgan Stanley can release shareholders early.
Where the IPO money goes
- The company gets the money from its new shares. It gets nothing from the shares the existing owners sell.
- Main uses: general business needs, including compute and data centers, and hiring and keeping staff.
- Some may go on buying or investing in other businesses. No deals are agreed.
- Some will cover the tax withheld when staff share awards pay out at the IPO.
- The amount raised is blank until the price range is filed.
The money: Latest 12 months to 30 Sep 2026
Revenue
9 months to Sep 2026, against 9 months to Sep 2025 a year earlier.
| By year | Year to Dec 2025 | Year to Dec 2024 | Year to Dec 2023 |
|---|---|---|---|
| Revenue | $4,585M | $386M | $41M |
| Operating result | −$8,060M | −$2,980M | −$551M |
| Net result | −$41,965M | −$8,309M | −$1,531M |
| Cash from operations | −$2,637M | −$5,692M | −$1,627M |
Most of the net loss is not cash spent. Convertible notes, mostly Amazon's, convert into shares at very low prices, so their value rises with the company's value, and that rise is booked as a loss: $94.3 billion in the nine months to September 2026. The notes are carried at $130.5 billion though only $6.2 billion was lent. The operating result and cash from operations show the business itself. Anthropic has signed about $895 billion of compute and infrastructure commitments, $69.8 billion of it due in the 12 months after September 2026. The 2025 operating loss includes a $1.5 billion legal settlement.
Source: the company's S-1/A filed with the SEC.
The banks running the deal
Wall Street analysts can't rate it until it trades. These are the banks selling the shares, as named on the front of the filing, in order.
 Goldman Sachs & Co. LLC
 Morgan Stanley
 J.P. Morgan
 Citigroup
 Barclays
 Wells Fargo Securities
 BofA Securities
 Deutsche Bank Securities
 RBC Capital Markets
 BMO Capital Markets
 BNP PARIBAS
 Credit Agricole CIB
 Jefferies
 Mizuho
 MUFG
 TD Securities
 BTIG
 Capital One Securities
 Macquarie Capital
 Societe Generale
Latest news
- Anthropic files amended IPO papers with September-quarter results
The S-1/A adds the nine months to September 2026: revenue of $33.2 billion and $6.6 billion of cash from operations. MUFG joins as a 22nd bank. The price range is still blank.
- Anthropic files to list on Nasdaq as ANT
The first S-1 names Goldman Sachs and Morgan Stanley first among 21 banks and sets out the founder and trust control structure.
- 10-for-1 stock split
Each Class A and Class N share became ten, ahead of the IPO (S-1/A).
- Series H raises $45.7 billion
From May to June 2026 investors paid $58.90 a share in today's terms, valuing the company at about $1.0 trillion by our sum (S-1/A).
Key risks
- Staying at the frontier: the company says its success depends on keeping its AI models among the most capable, and rivals are spending heavily too.
- Compute bill: about $895 billion of compute and infrastructure commitments, with $69.8 billion due in the 12 months after September 2026.
- Growth may slow: the company expects its growth rate to fall, and models released in the six months to September made up over 80% of September-quarter revenue.
- Few suppliers: it relies on a small number of cloud providers that are also investors, customers and competitors.
- Harm and the law: misuse of its models, or models acting in ways nobody intended, could bring lawsuits, regulation and damage to the brand.
- No real say for buyers: IPO shareholders are capped at 49.9% of the votes, a trust picks most of the board, and the board must weigh its public purpose against returns.
- Dilution: options on 1.77 billion shares, $24.1 billion of staff share pay not yet expensed, and up to 2% extra shares for its public benefit fund each time the price rises 50%.
SEC filings
Beast Scores and Beast Calls (Buy, Hold, Sell) are the opinions of StockBeast, published for general information and education. The same ratings are provided to every subscriber. They are not personalized investment advice and do not take into account your financial situation, objectives or needs. StockBeast is not a registered investment adviser or broker-dealer.
Investing in stocks involves risk, including the possible loss of your entire investment. Ratings can change at any time and may be wrong. Wall Street analyst ratings shown are third-party opinions. Prices are closing prices, not live quotes. StockBeast, its owners and contributors may hold positions in securities discussed. Do your own research and consider speaking with a licensed financial professional before making any investment decision.